2026 Aluminum Storm: Navigating Geopolitical Turmoil and Record-High Costs
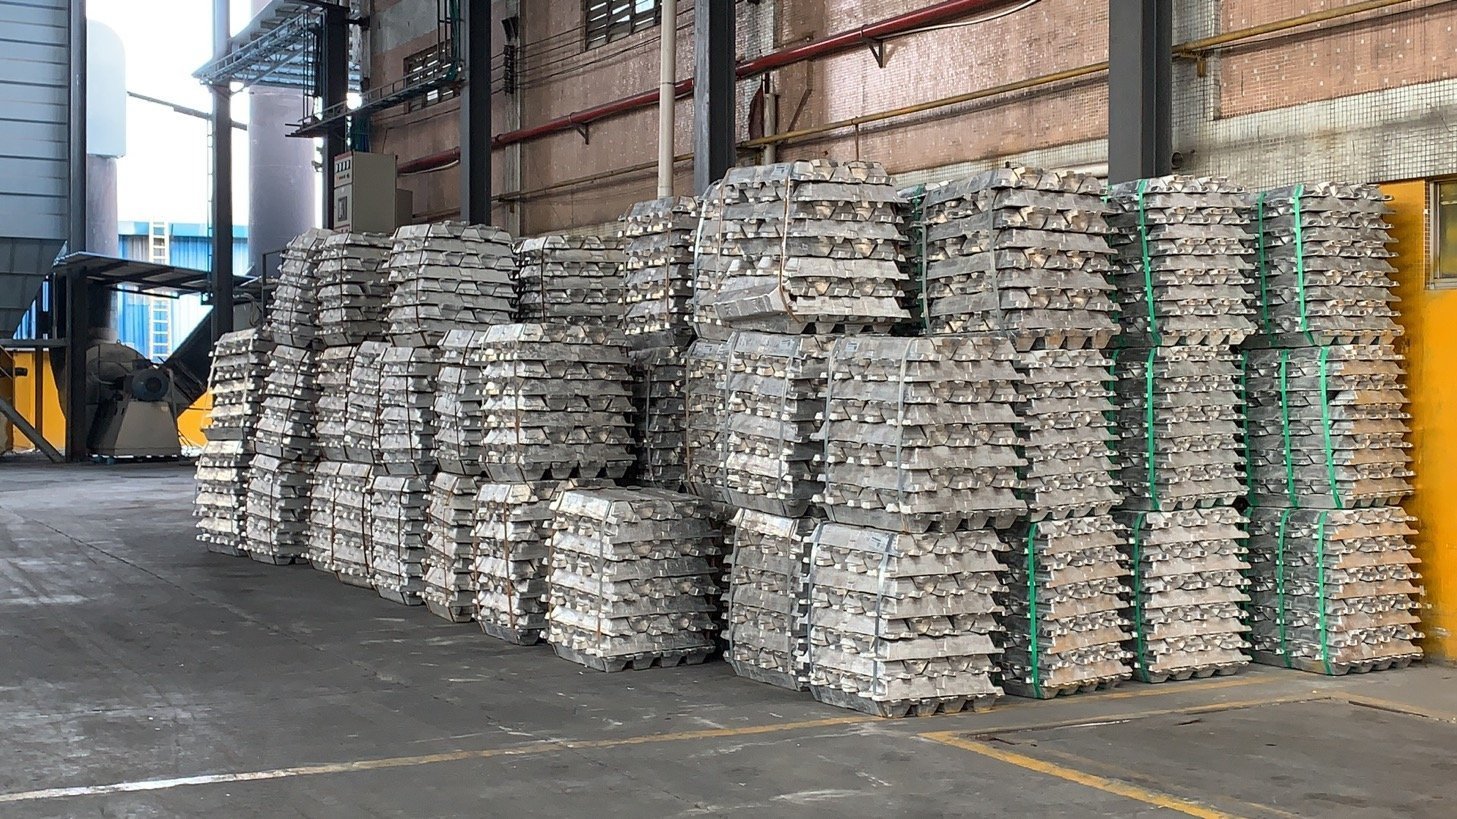
LME aluminum has surged toward $3,600 per tonne, up 35% year on year, as the Strait of Hormuz closure paralyses nearly 9% of global supply and a 50% tariff drives the US Midwest Premium above $1 per pound.
The Most Volatile Phase in Decades
The global aluminum market has entered its most volatile phase in decades. As of May 2026, LME aluminum prices have surged toward $3,600 per tonne - a 35% year-on-year increase. Driven by the closure of the Strait of Hormuz and aggressive new tariff regimes, the industry is shifting from a cost-first model to a security-first procurement strategy.
For anyone buying extruded profiles, that shift changes the questions worth asking. Price still matters, but continuity, origin and quoting mechanics now decide whether a project actually ships.
The Perfect Storm: Why Prices Are Rising
The current price action is a structural shift caused by three converging forces.
- Geopolitical chokepoints. The closure of the Strait of Hormuz has paralysed nearly 9% of global aluminum supply, causing an immediate liquidity crunch for high-quality primary aluminum.
- The tariff effect. With a 50% tariff looming under 2025 trade policies, the US Midwest Premium has surpassed $1 per pound for the first time in history, placing an immense burden on downstream manufacturers.
- Manufacturing under pressure. Global manufacturers including Ford and Molson Coors have reported record-high input costs, forcing a ripple effect across the entire architectural aluminum sector.
Two of those three forces are policy-driven and therefore reversible on a political timetable. The third - a physical chokepoint affecting roughly one eleventh of world supply - is not something a buyer can wait out with a spreadsheet.
What the Numbers Say About 2026 and 2027
| Period | Market view |
|---|---|
| May 2026 spot | LME aluminum near $3,600 per tonne, up 35% year on year |
| 2026 annual average | Prices expected to remain elevated, averaging around $3,400 per tonne |
| 2027 projection | A soft landing toward $3,200 per tonne as supply chains reroute and the market adjusts to the new tariff landscape |
The forecast shape matters as much as the levels. Even the softer 2027 view sits far above the range buyers were planning against three years ago. A soft landing is not a return to the old normal.
Why Security-First Replaced Cost-First
When spot markets move by the hour, the cheapest quote on Monday can be the most expensive decision by Thursday. Procurement teams that optimized purely on unit price have discovered the cost of the alternative: re-quoting mid-project, absorbing metal risk they cannot hedge, and explaining schedule slips to customers.
The practical response is not to abandon cost discipline. It is to price continuity explicitly and to choose suppliers whose commercial mechanics are transparent enough to plan around.
Quoting Discipline: The Weekly Fixed Quote System
In a market where prices can fluctuate by the hour, Linkedalu Metal Group operates a weekly fixed quote system designed to give buyers predictability:
- The Monday quote. Every Monday a fixed price is issued for aluminum profiles based on current market data.
- Weekly validity. That price remains valid until Friday, allowing buyers to bid on projects and manage cash flow with confidence.
- The stability trigger. A quote is only adjusted mid-week if the cost of aluminum ingots fluctuates by more than US$45 per tonne. Minor market noise is absorbed by the supplier rather than passed through.
Engineering for Cost Efficiency Above $3,500 Per Tonne
When aluminum exceeds $3,500 per tonne, every gram matters. Engineering support should help redesign profiles - leveraging the superior strength-to-weight ratio of 6063-T5 - to reduce wall thickness without compromising structural integrity. Done properly, this is a technical exercise with inspection data behind it, not a cosmetic thinning of the section.
Supply Continuity
With the new tariff landscape, the origin of aluminum is critical. Maintaining a strategic raw material buffer supports a 15 to 25 day lead time, so projects stay on schedule even when global spot markets are tight. That buffer is a working capital decision, and it is one of the clearest signals of whether a supplier intends to be a long-term partner.
What Buyers Should Do This Quarter
- Ask every supplier how their quote validity works and what triggers a mid-week revision.
- Confirm the alloy and temper you are actually being quoted, and stop paying for properties the application does not need.
- Re-examine wall thickness and section geometry with your extruder while metal is expensive.
- Verify lead-time commitments in writing, and ask what raw material buffer stands behind them.
- Diversify origin, but consolidate finishing standards so quality does not fragment with sourcing.
Stability as a Deliverable
Twenty years of extrusion experience teaches one durable lesson: volatility is inevitable and unmanaged volatility is optional. Turning market chaos into a manageable business variable - through transparent weekly pricing and genuine engineering support - is a better answer than a daily price list nobody can plan against. Companies that partner with transparent, stable-pricing suppliers today will be the ones best positioned when prices stabilize in 2027.
Customer reviews
No reviews yet — be the first to review 2026 Aluminum Storm: Navigating Geopolitical Turmoil and Record-High Costs.
Write a review
Reviews are read by our team before they appear here, usually within one working day. We publish what customers write; we only remove spam and abuse.
Keep reading
 Insights
Europe Can't Make Its Own Aluminium Anymore — What 2026–2030 Looks Like for B2B Buyers
Europe's primary aluminium self-sufficiency has fallen below 13%, the Middle East conflict has knocked out 2.3 Mt of supply, and the…
Read article arrow_forward Insights
starFeatured
The Structural Break in Global Aluminum
China hit its 45 Mt aluminum ceiling, Guinea signalled an export cap, Rusal is sanctioned and a Gulf smelter curtailed in February 2026…
Read article arrow_forward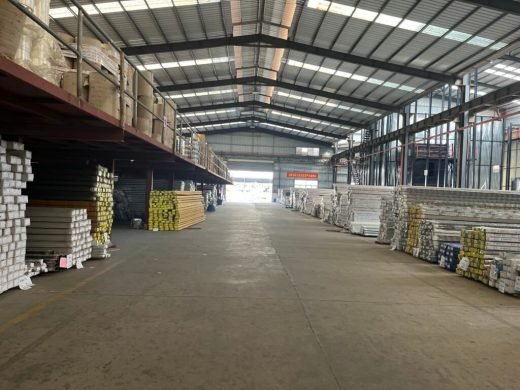 Insights
starFeatured
Tariffs, R&D, and the Myth of the Fragile Chinese Factory
Four headlines from WSJ, the New York Times and Nikkei appear to contradict each other. Read together, they explain why production is…
Read article arrow_forward